


There is no doubt that there is a variety of CIMA F2 exam resources in the internet for the IT exam, and we know the more choices equal to more trouble, so we really want to introduce the best one to you and let you make a wise decision. It is said that a good beginning makes for a good ending. Therefore it goes naturally that choosing the right study materials is a crucial task for passing exam with good F2 pass score. We are so glad to know that you have paid attention to us and we really appreciate that, we will do our utmost to help you to pass the IT exam as well as get the IT certification. Owing to the high quality and favorable price of our F2 test prep materials, our company has become the leader in this field for many years. There is really a long list to say about the strong points of our F2 exam resources, including less time for high efficiency, free renewal for a year, to name but a few.

Less time for high efficiency
As everyone knows, preparing for an exam is a time-consuming as well as energy-consuming course, however, as it is worldly renowned well begun, half done, if you choose to use our F2 test prep materials, you can save most of your time as well as energy since we can assure that you can pass the IT exam and get the IT certification with a minimum of time and effort. The contents in our CIMA F2 exam resources are all quintessence for the IT exam, which covers all of the key points and the latest types of examination questions and you can find nothing redundant in our F2 test prep materials. Therefore, you can finish practicing all of the essence of IT exam only after 20 to 30 hours. After practicing all of the contents in our F2 exam resources it is no denying that you can pass the IT exam as well as get the IT certification as easy as rolling off a log.
Free renewal for a year
Once you buy our F2 test prep materials, during the whole year, as soon as we have compiled a new version of the exam study materials, our company will send the latest one to you for free. Our top IT experts are always keep an eye on even the slightest change in the IT field, and we will compile every new important point immediately to our CIMA F2 exam resources, so we can assure that you won't miss any key points for the IT exam. And please think about this, as I just mentioned, in the matter of fact, you can pass the exam with the help of our exam study materials only after practice for 20 to 30 hours, which means it is highly possible that you can still receive the new F2 test prep materials from us after you have passed the exam if you are willing, so you will have access to learn more about the important knowledge of the IT industry or you can pursue wonderful F2 pass score, it will be a good way for you to broaden your horizons as well as improve your skills. You can see it is clear that there are only benefits for you to buy our CIMA F2 exam resources, so why not have a try?
After purchase, Instant Download: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
CIMA F2 Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Financing capital projects | 15% | |
| Financial reporting standards | 25% | |
| Group accounts | 25% | |
| Integrated reporting and sustainability reporting | 10% | |
| Analysing financial statements | 25% |
CIMA Advanced Financial Reporting Sample Questions:
JK has calculated its inventory holding period: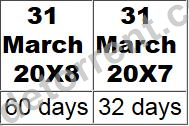
Which THREE of the following would have contributed to the above movement in inventory holding period?
- A. It has been difficult to obtain one of JK's main components due to import issues with its overseas supplier.
- B. JK is enforcing stringent inventory control techniques following management instructions.
- C. JK suffered industrial action by its production staff in the period December 20X7 to February 20X8.
- D. JK's main supplier offered a significant one-off discount for purchases made in March 20X8.
- E. In January 20X8 a major competitor entered the market in which JK operates.
- F. A substantial contract is due to be dispatched early in April 20X8.
Correct Answer: D,E,F 🗳️
EFG is preparing its financial statements to 31 March 20X8. During the year ended 31 March 20X7, EFG purchased a piece of land for $1 million which is used as the staff car park. EFG has a policy of revaluing land, in accordance with International Accounting Standards, and at 31 March 20X8, accounted for a substantial increase in its value.
Revenue and operating profit has remained constant over the 2 years.
When comparing EFG's financial statements for the year ended 31 March 20X7 with those of 20X8, which THREE of the following would be expected?
- A. Increase in other comprehensive income.
- B. Increase in profit before tax.
- C. Decrease in return on capital employed.
- D. Decrease in net asset turnover.
- E. Increase in return on capital employed.
- F. Increase in net asset turnover.
Correct Answer: A,C,D 🗳️
On 1 January 20X6 AB, a listed entity, had 10,000,000 $1 ordinary shares in issue. On 1 April 20X6 AB issued 3,000,000 $1 ordinary shares at their full market price. AB's profit was reported as $1,100,000 after charging corporate income tax of $500,000.
Place the correct values for profit and weighted average number of shares in the boxes below that will be used to calculate AB's earnings per share for the year to 31 December 20X6.
Correct Answer:

LM and JK operate in the same country and prepare their financial statements to 30 June 20X6 in accordance with International Accounting Standards. On 27 June 20X6 both entities raised $1 million cash by issuing debt instruments with identical terms and conditions. Prior to this issue both entities were financed entirely by equity.
At 30 June 20X6 the gearing ratios, calculated as Debt/Equity x 100%, were as follows:
LM: 30%
JK: 65%
Which of the following independent options would explain the difference between LM and JK's year-end gearing?
- A. LM had 100,000 $1 shares at the year end; JK had 200,000 50c shares in issue at the year end.
- B. LM made a bonus issue from retained earnings in the year; JK issued no shares in the year.
- C. LM held no investments in other entities; JK revalued its available for sale investments upwards in the year.
- D. LM revalued its land and buildings upwards in the year; JK has performed no revaluations.
Correct Answer: D 🗳️
WX acquired 60% of the equity shares of CD on 1 January 20X3. WX sold 5% of the equity shares it held for $60,000 on 31 December 20X5. At that date the net assets of CD were $120,000 and the fair value of the non-controlling interest in CD was measured at $21,000. No goodwill arose on the original acquisition of CD.
When preparing its consoldiated financial statements, WX will process which of the following adjustments to its group retained earnings?
- A. A credit of $39,000
- B. A debit of $39,000
- C. A credit of $54,000
- D. A debit of $54,000
Correct Answer: C 🗳️


